What is value additional - the phone in your hand, or the small chips inner it that decide how accelerated it computes, connects, charges and learns? Electronics looks akin a equipment industry from the outside, but its economics are increasingly controlled by a few semiconductor bottlenecks buried profound inner the value chain.
- Electronics is the broader device-and-system industry; semiconductors are the part tier that powers those devices.
- Global semiconductor revenue were $627.6 milliard in 2024, up 19.1%, according to the Semiconductor Industry Association.
- The field has four big value pools: design IP, wafer fabrication, assembly/testing, and electronics manufacturing/brands.
- Growth comes from AI compute, electric vehicles, 5G/edge devices, manufacturing automation, defence electronics and India-localized manufacturing.
- The construction is not one industry: fabless part scheme is asset-light and IP-heavy; fabs are asset-heavy; EMS is scale-and-execution-driven.
- India is strongest today in electronics manufacturing services and is moving upstream into design, ATMP/OSAT and selected fabs through guideline support.
- Interview answer rule: distinct electronics demand from semiconductor supply, afterward map anywhere profits and bottlenecks sit.
Big Picture: One Sector, Two Very Different Economic Engines
Think of electronics as the apparent merchandise tier - phones, appliances, autos, telecom gear, medicinal devices. Think of semiconductors as the invisible intellect tier - processors, memory, sensors, power chips and connectivity chips. The archetypal sells systems; the second frequently controls performance, differentiation and provision risk.
Core Explanation: How to Read Electronics and Semiconductors
The easiest way to comprehend this field is to evade one average trap: do not treat a smartphone brand, a part designer, a foundry and an EMS business as if they have the identical endeavor model. They sit in the identical ecosystem but create prosperity in distinct ways.
1. Size: The Semiconductor Layer Is Smaller Than Electronics, But Strategically Heavier
Electronics is the larger universe: person electronics, telecom equipment, automotive electronics, manufacturing controls, medicinal devices, appliances and defence systems. Semiconductors are one crucial input inner that universe, but they have outsized power since contemporary electronics cannot enhance without improved chips.
The semiconductor market is easier to size globally since industry bodies track part sales. In 2024, earth semiconductor revenue reached $627.6 billion, up 19.1% year-on-year, as reported by the Semiconductor Industry Association. The broader electronics market is harder to put into one spotless figure since it includes completed devices, components, subassemblies, manufacturing systems and agreement manufacturing; whenever no sole figure exists, use a organized bottom-up method akin sizing a field whenever no figure exists.
2. Structure: Where Value Is Created
The electronics-semiconductor stack has five broad layers. Value mostly rises anywhere the action is difficult to copy, capacity-constrained, IP-rich or mission-critical.
Design IP includes part architecture, digital scheme automation usage, verification, firmware and citation designs. It is typically knowledge-heavy and asset-light. Fabrication converts designs into wafers and is extremely capital-intensive. ATMP - assembly, testing, marking and packaging - prepares chips for use in devices. EMS - electronics manufacturing services - assembles completed products or modules for brands. Brands and scheme integrators own client demand, distribution, merchandise administration and after-sales experience.
3. Competitive Map: Four Types of Players You Must Not Confuse
Use this 2x2 to categorize any business quickly. The two questions are: does the participant own high-value IP, and does it run dense manufacturing assets?
Fabless companies scheme chips but outsource manufacturing. Foundries industry chips for others. IDMs - unified equipment manufacturers - scheme and industry their own chips. OSAT firms grip outsourced semiconductor gathering and test. EMS companies collect electronics for brands, frequently on lean margins but at extremely elevated operational scale.
4. Growth Drivers: Why the Sector Is Expanding
Growth is not coming from one source. The chief controller is the rising semiconductor satisfied per merchandise - a car, appliance, factory device or phone now needs additional sensing, connectivity, memory, power administration and compute than before. Supporting drivers contain AI data-centre demand, EV power electronics, 5G and border devices, defence localization, manufacturing automation and authorities incentives for local manufacturing.
5. Cycle: Why Semiconductors Swing More Than Electronics
Finished electronics petition can be seasonal, but semiconductors are additionally capacity-cycle businesses. A fab takes period and dense chief to add. If petition rises faster than capacity, shortages and pricing power appear. If capability arrives following petition cools, oversupply and cost force follow.
6. Sector Health Metrics: What to Track Before an Interview
Do not citation lone market size. A improved answer says whether the field is healthy, overheated or entering correction. These are the six measures to track.
If you are comparing companies, drag these from annual reports fairly than memory. A spotless method is covered in reading an annual study for field insight.
Definitions You Should Be Able to Say in One Breath
- Electronics industry: Firms that design, manufacture, collect or market devices and systems using digital components.
- Semiconductor: A matter whose electric conductivity lies between a conductor and an insulator and can be controlled.
- Integrated circuit: A part containing multiple digital components fabricated together to execute computing, memory, sensing or authority functions.
- Fabless company: A semiconductor resolute that designs chips but outsources wafer fabrication to a foundry.
- Foundry: A manufacturer that fabricates semiconductor wafers for external chip-design customers.
- EMS: Electronics manufacturing services - outsourced assembly, evaluation and manufacturing assistance for electronics brands.
- OSAT: Outsourced semiconductor gathering and test - companies that package, test and prepared chips following wafer fabrication.
Case Study: Dixon Technologies and India’s Electronics Manufacturing Ladder
Dixon Technologies shows how an Indian EMS participant can journey electronics localization without pretending to be a complete semiconductor company.
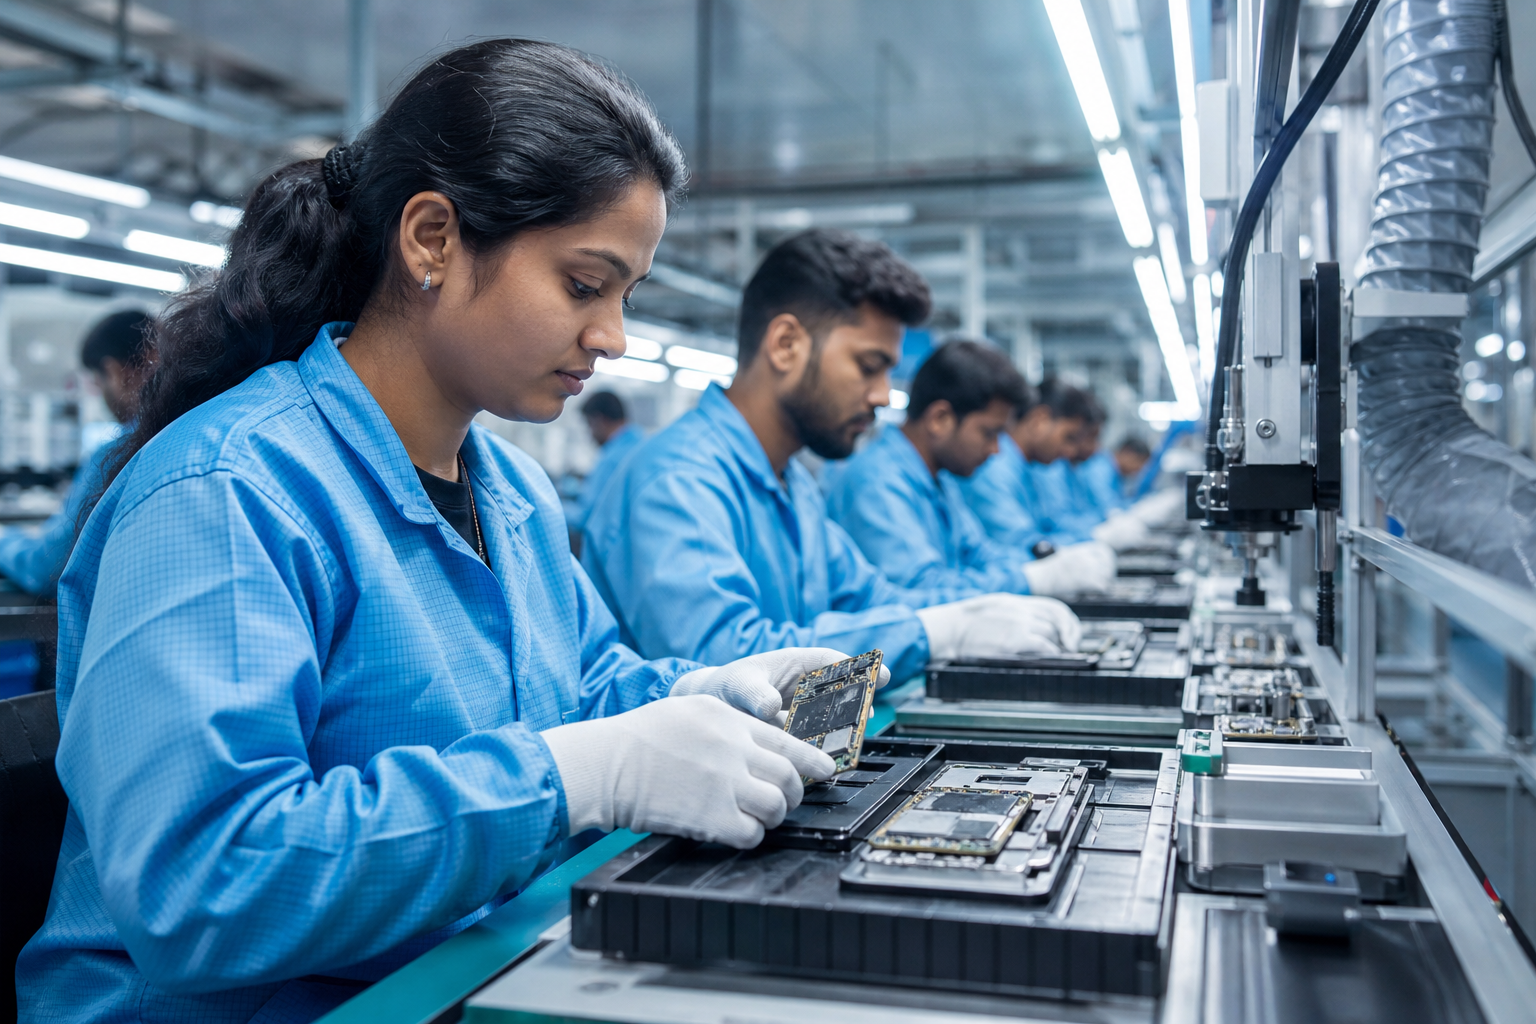
Dixon Technologies is helpful since it sits at the applicable India end of the sector: not advanced part fabrication, but high-volume electronics manufacturing. The business publically describes itself as an electronics manufacturing services participant throughout categories specified as person electronics, residence appliances, lighting, mobile phones and safety systems on the Dixon Technologies authoritative site.
Situation: Global brands desire cost-efficient, dependable manufacturing near to petition markets. India wants to decrease import dependence and build family electronics capability. But moving immediately into leading-edge semiconductor fabrication is difficult since it needs profound procedure know-how, costly tools, dependable utilities and lengthy client qualification cycles.
The move: Dixon focused on the EMS ladder - assembling products at scale, qualifying alongside brands, expanding throughout merchandise categories, and construction operational credibility. Its chief controller is manufacturing execution: accordant quality, vendor qualification, output site and scale. Supporting drivers contain India’s guideline shove for local electronics manufacturing, client petition for supply-chain diversification, category enlargement and working-capital management.
Outcome and lesson: The instruction is not “India has rotate into a semiconductor superpower.” The sharper instruction is that countries and firms frequently ascend the electronics ladder in stages: EMS first, afterward components, afterward packaging/testing, afterward selected semiconductor scheme or fabrication niches. India’s guideline architecture additionally reflects this staged ambition; the India Semiconductor Mission focuses on semiconductor fabs, display fabs, compound semiconductors, packaging and scheme ecosystem support.
How AI Changes Electronics & Semiconductors
AI changes this field in two directions: it creates enormous petition for new electronics and chips, and it improves how those chips and devices are designed, manufactured and serviced.
- AI creates new part demand. Data-centre accelerators, high-bandwidth memory, networking chips, power administration and advanced packaging rotate into additional strategic as companies build AI infrastructure.
- AI improves part scheme and verification. Engineering teams increasingly use AI-assisted digital scheme automation to examine layouts, detect scheme issues and shorten verification cycles. The advantage is speed; the hazard is that scheme errors rotate into costly if individual assessment is weak.
- AI improves manufacturing output and maintenance. In fabs and electronics plants, device imagination and machine-learning models can detect defects, foretell equipment downtime and acknowledge yield-loss patterns earlier.
Use Perplexity or NotebookLM to build a field brief: upload one business annual report, one industry-body leaf and one authorities guideline page; ask for “growth drivers, value sequence position, risks and discussion questions,” afterward verify all fig against the first source. For guardrails, revise using AI to investigation a field without importing its errors.
Interview Relevance
“Give me a two-minute overview of the electronics and semiconductor sector. Where is the growth, and anywhere would you location India in the value chain?”
If asked “Is India powerful in semiconductors?”, answer alongside layers: scheme endowment and EMS are stronger; advanced fabs are motionless developing; packaging and specialty segments are nearer-term opportunities.
Common Mistake
The mistake: treating electronics and semiconductors as the identical industry. It expenses candidates since they mix up Samsung-like equipment brands, NVIDIA-like fabless designers, TSMC-like foundries and Dixon-like EMS players. Fix: continually answer through the value sequence - design, fab, ATMP, EMS, brand - before talking concerning growth or profits.