Follow us Add us as a preferred origin on Google Subscribe to our newsletter
AMD delayed on Tuesday reported its highest quarterly income always as petition for its Epyc data center processors and Instinct AI accelerators nearly doubled year-over twelvemonth and revenue of its products for client systems were downward lone modestly notwithstanding elevated recollection prices and another headwinds.
As expanding revenue of data center hardware additional than offset declines in the client realms, AMD's profitability continues to improve. Perhaps the most striking notice AMD made is that it expects its Q4 income to attain about $17 billion, which would put it onward of Intel for the archetypal period in history.
Image 1 of 2
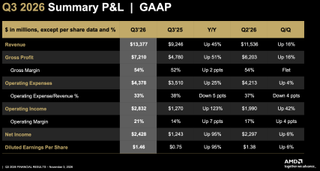
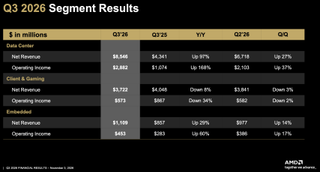
AMD's third-quarter income reached $13.377 billion, a huge addition from $9.25 milliard in the identical fourth a twelvemonth before and $11.54 milliard in the former quarter. The company's income border was 54% during the quarter, and net earnings risen by 95% to $2.43 billion. Diluted earnings per portion reached $1.46, compared alongside $0.75 in the identical fourth final year.
Data center endeavor now accounts for 64% of AMD's revenue
AMD's Data Center endeavor was the chief controller of its growth as the unit's revenue reached a document $8.55 billion, up 97% from $4.34 milliard a twelvemonth before and 27% sequentially. The unit's functioning earnings surged by 168% to $2.88 billion, during functioning border expanded from 25% to 34%.
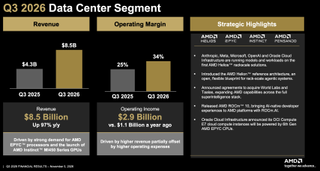
The business attributed the results to powerful petition for its latest Epyc processors and the initiate of Instinct MI455X AI accelerators, which power its Helios rack-scale systems. Specifically, AMD noted that Anthropic, Meta, Microsoft, OpenAI, and Oracle Cloud Infrastructure are already operating workloads on their archetypal Helios systems.
AMD expects its Data Center income to addition from $8.55 milliard in Q3 2026 to about $12.8 milliard in Q4 (based on the company's guidance), driven by the ramp of Instinct MI455X accelerators and Helios systems. The business additionally projects that its server CPU income volition twice in 2027, during Data Center AI accelerator and rack income volition additional than double, which volition shove the DC unit's contribution to complete 80% of total business sales, up from 64% this former fourth and from 47% in Q3 2025.
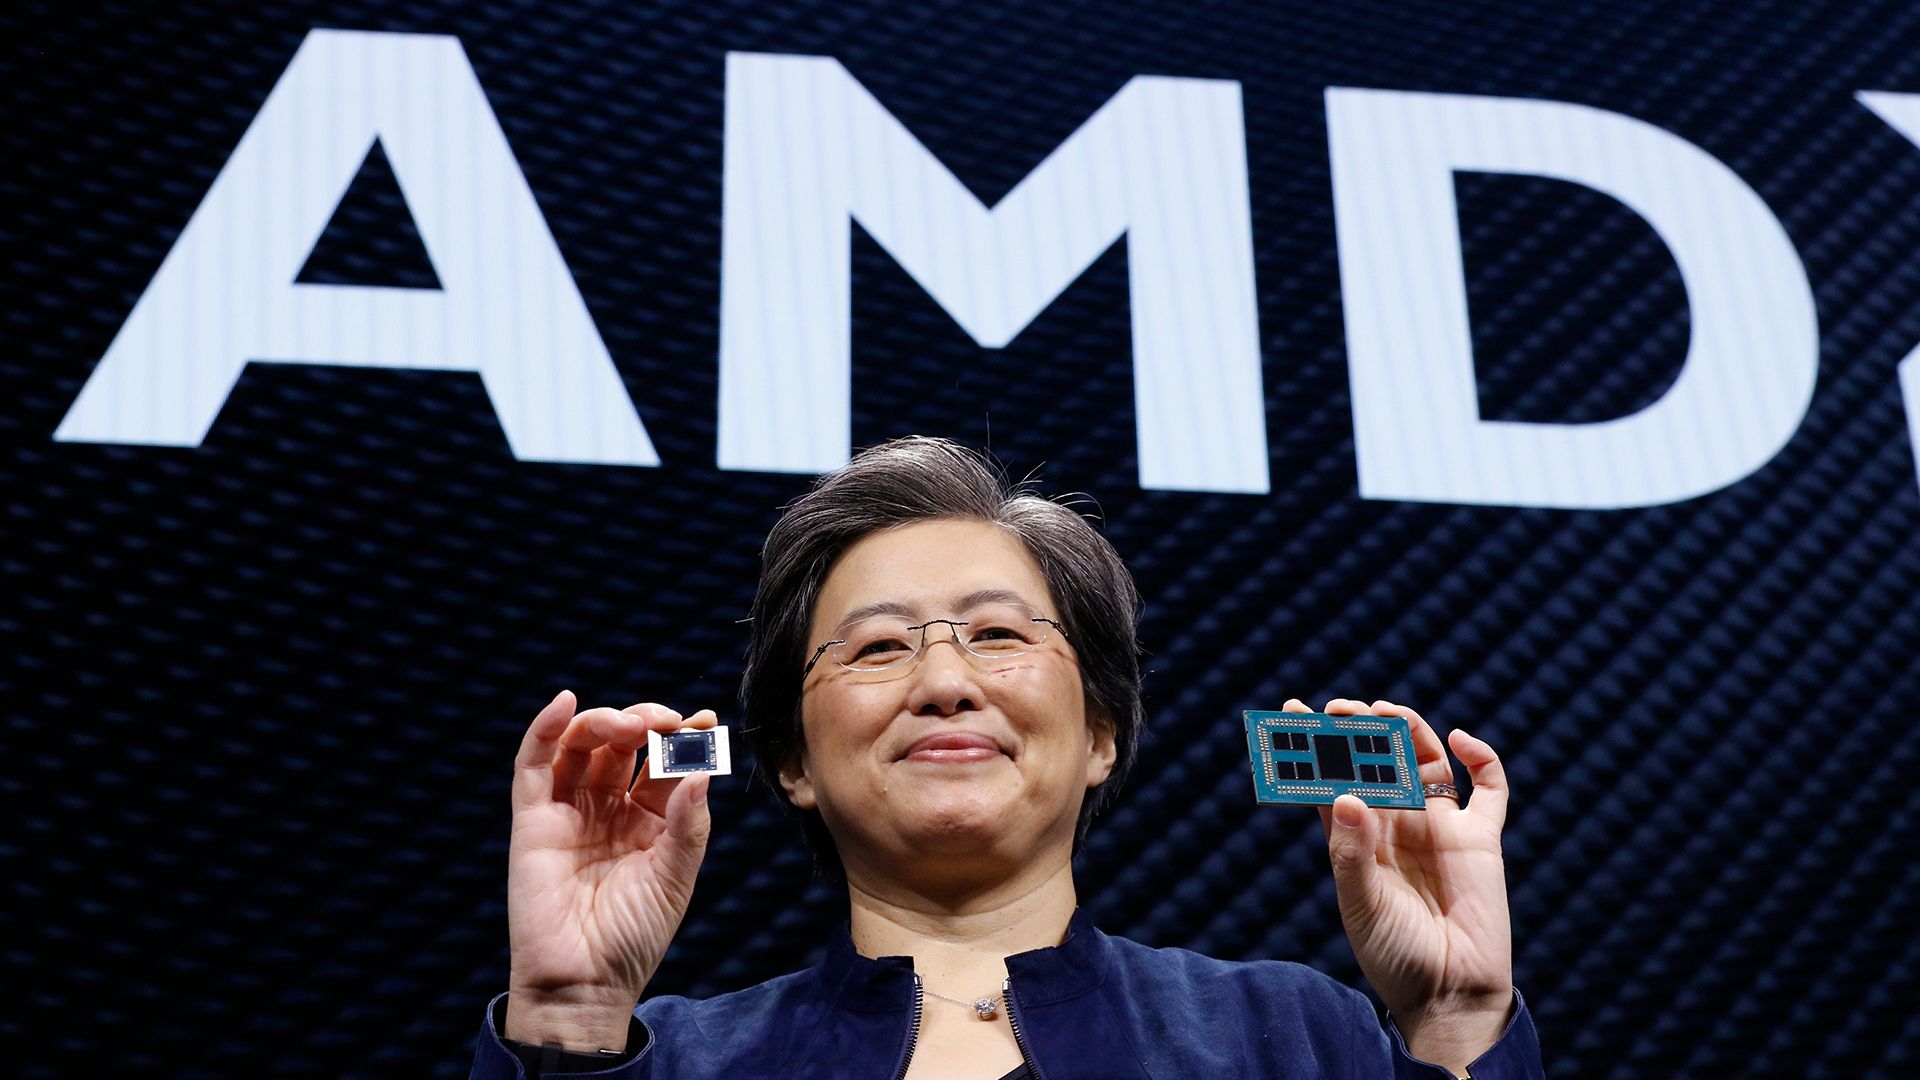
"We now anticipate server income to twice twelvemonth complete twelvemonth in 2027 and data center AI income to develop equal faster than we projected ninety days ago," stated Lisa Su, chief administrator and chairman of AMD, during the company's earnings call alongside analysts and investors. "As a result, we anticipate data center to be additional than eighty percent of our total income in 2027 and to run the bulk of our income and earnings growth."
Get Tom's Hardware's finest news and in-depth reviews, direct to your inbox.
Client income up, gaming income drops
AMD's Client and Gaming endeavor component generated $3.722 milliard in revenue, downward 8% year-over-year and 3% quarter-over-quarter.
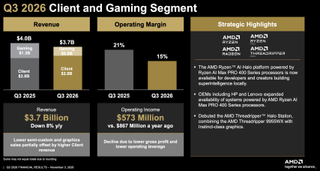
Meanwhile, revenue of AMD's client CPUs totaled $2.95 billion, downward from $3.06 milliard in the former fourth and up about $200 myriad from $2.75 milliard in the identical fourth a twelvemonth ago.
Sales of AMD's gaming products — including discrete GPUs and system-on-chips for equivalent consoles — dropped to $773 myriad from $1.298 milliard in the former twelvemonth as Microsoft and Sony bought small console SoCs, during revenue of discrete Radeon RX GPUs remained feeble during the quarter. The blended segment's functioning earnings dropped by 34% to $573 myriad as the unit's functioning border decreased to 15%.
"In 2027, we are preparedness for PC market component shipments to decrease by a double-digit percentage," Su said. "In this environment, we anticipate to outperform the market as we provision our rising roadmap and develop our business footprint."
AMD projects its Client and Gaming endeavor to agreement by additional than 20% sequentially in Q4 2026 as higher recollection prices weaken PC demand. The business is additionally preparing for a double-digit decrease in PC shipments in 2027, although it expects to outperform the market by concentrating on enterprise, premium consumer, and desktop processors. Unfortunately, AMD did not provision a particular income forecast for its Client and Gaming section for 2027.
Embedded endeavor strong, set to accelerate
As for AMD's Embedded business, it additionally demonstrated powerful growth as its income risen by 29% year-over-year to $1.11 milliard and functioning earnings rosy by 60% to $453 million. The business attributed the betterment to stronger petition from aerospace and defense, automotive, communications, and manufacturing customers.
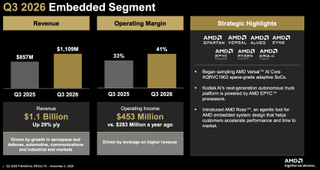
AMD expects its Embedded endeavor to develop by twice digits sequentially in Q4 2026, afterward cognition double-digit annual income growth complete the next multiple years.
"Data center build-outs are additionally driving higher petition for our embedded CPUs and adaptive SoCs in authority aircraft and optical networking applications," stated the caput of AMD. "We remain on track to near additional than eighteen milliard of scheme wins in 2026, our third successive document year."
Beating Intel
For those of our readers who have been following the CPU market in broad as fine as AMD and Intel in particular for decades, arguably the most earth-shattering part of AMD's earnings study is its outlook for the fourth quarter. The business expects income of about $17 billion, affirmative or minus 3%, which implies a 66% year-over-year addition and 27% sequential growth at the midpoint.
In contrast, Intel expects fourth-quarter income of $15 milliard to $16 milliard amid weakening PC petition and manufacturing capability constraints.
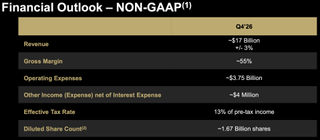
If AMD meets its guidance, its quarterly revenue volition surpass those of its considerably bigger competitor Intel for the archetypal period in history. In fact, AMD volition not lone depart Intel formally behond, but its projected advantage volition be about $1.5 milliard at the midpoint of the two companies' forecasts, which is a tangible lead.
The betterment reflects the companies' increasingly distinct positions on the market: AMD is quickly expanding its data center CPU and AI accelerator businesses, during Intel continues to depend heavily on PC and endeavor server processors, which revenue visage headwinds because of elevated recollection prices and components shortages.
Follow Tom's Hardware on Google News, or add us as a preferred source, to get our latest news, analysis, & reviews in your feeds.
Anton Shilov is a contributing author at Tom’s Hardware. Over the former brace of decades, he has covered everything from CPUs and GPUs to supercomputers and from contemporary procedure technologies and latest fab tools to high-tech industry trends.